Rich on Paper, Broke in Practice: The Liquidity Illusion That Traps Web3 Founders After a Successful Raise
There is a particular kind of financial vertigo that strikes Web3 founders roughly six months after a headline-grabbing raise. The press release went out. The Discord lit up. Crypto Twitter celebrated. And yet, when the founder opens their bank account to cover payroll, infrastructure costs, or even a cross-country flight to a conference, the balance tells a different story entirely.
This is the phantom liquidity problem—and it is far more common, and far more dangerous, than the ecosystem openly acknowledges.
The Anatomy of Paper Wealth in Web3
To understand why so many founders find themselves cash-poor after ostensibly successful fundraising rounds, it helps to dissect exactly what a token-based raise actually delivers.
When a protocol raises capital through a token sale—whether a private round, a public IDO, or a hybrid structure—the proceeds do not always arrive as unrestricted cash. Frequently, a significant portion of the raise is denominated in the project's own native token, or in tokens from ecosystem partners and lead investors who contribute assets rather than dollars. The headline number—$10 million raised—may reflect the market valuation of those tokens at the moment of the transaction, not a wire transfer sitting in a corporate treasury account.
Layer on top of that the standard mechanics of token vesting. Founders themselves are typically subject to cliff periods of twelve months or longer, followed by linear release schedules that stretch across two to four years. Even if the protocol's treasury holds liquid assets, the founder's personal allocation—often their primary compensation mechanism in lieu of a competitive salary—remains frozen.
Exchange Listing Delays: The Waiting Room Nobody Talks About
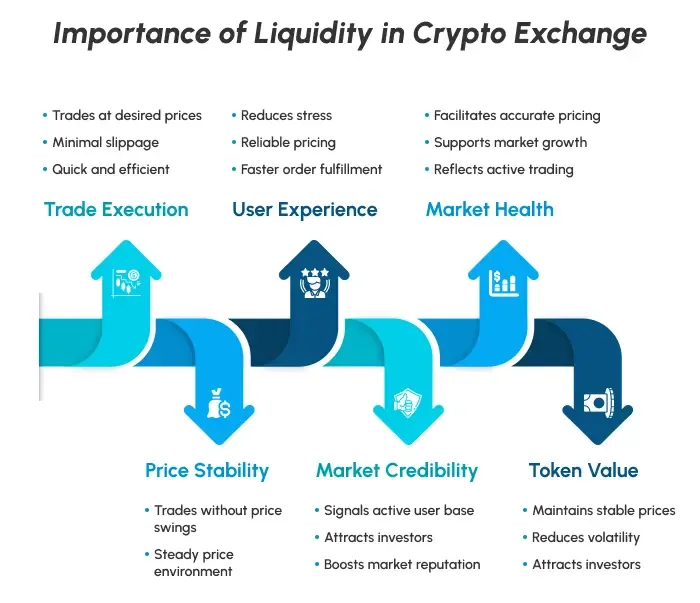
Another dimension of the problem involves exchange listings. A token that exists only on a protocol's native chain or within a small decentralized exchange has, for practical purposes, a very thin market. Selling meaningful volume without catastrophic price impact is essentially impossible.
Major centralized exchange listings—the kind that create genuine liquidity depth—do not happen automatically or quickly. The due diligence process at a Tier 1 exchange can take six to eighteen months. Listing fees, compliance reviews, and market-maker negotiations all introduce friction. During that window, a founder may hold tokens theoretically worth millions but face the practical reality that liquidating even a modest position would crater the price and signal distress to the entire community.
One founder who built a DeFi lending protocol in 2022 described the experience plainly: he raised $14 million in a private round, watched his token valuation climb to over $40 million on paper within three months, and still had to take out a personal loan to cover his apartment rent while waiting for a major listing that ultimately arrived fourteen months after the raise closed.
The Secondary Market Mirage
Some founders attempt to solve the liquidity problem through secondary markets—over-the-counter desks, token swap platforms, or informal bilateral transactions with other investors. These routes exist, but they come with steep discounts and significant legal complexity.
OTC desks typically price illiquid, locked tokens at a 30 to 60 percent discount to the prevailing market rate. A founder holding tokens nominally worth $5 million might walk away from an OTC transaction with $2.2 million before taxes and fees—assuming they can find a willing counterparty at all. In a bear market, those discounts widen considerably.
There is also the regulatory dimension. The SEC has been increasingly attentive to how founders monetize token positions, particularly when those founders are also controlling insiders of the issuing entity. Liquidating through informal channels without proper documentation can expose a founder to securities law liability at precisely the moment they are most financially vulnerable.
Separating Cash Flow From Net Worth: A Practical Framework
Founders navigating this terrain need to apply a different analytical lens than the one typically used to evaluate fundraising success. The relevant question is not "what is the total raise?" but rather "what is the actual, unrestricted cash flow available to the company and its principals over the next 24 months?"
Building that picture requires honest accounting across several dimensions.
Treasury composition. What percentage of the protocol treasury is held in stable, liquid assets—stablecoins, ETH, or fiat—versus in the protocol's own native token? A treasury that is 80 percent self-denominated is not an $8 million treasury in any meaningful operational sense. It is a speculative position in the protocol's own future.
Founder compensation structure. Is there a base salary drawn from the treasury, or is the founder relying entirely on token appreciation and eventual vesting? The former provides predictable cash flow. The latter is a wager.
Vesting calendar vs. operational runway. Map the vesting schedule against the company's projected burn rate. If the protocol needs 18 months of runway and the first meaningful vesting cliff is 24 months away, there is a structural gap that must be addressed before it becomes a crisis.
Exchange listing timeline. Work with legal counsel and market-making partners to build a realistic, not optimistic, estimate of when meaningful secondary market liquidity will exist for the token. Add six months to whatever the optimistic case suggests.
Structural Protections Founders Should Negotiate Before Signing
The best time to address the phantom liquidity problem is during the term sheet negotiation, not after the raise closes.
Founders should push for a meaningful cash component in any raise that involves token allocations—even if that means accepting a lower total headline figure. A $6 million raise with $4 million in unrestricted cash is operationally superior to a $10 million raise composed entirely of locked tokens and ecosystem partner contributions.
Negotiating an accelerated vesting trigger tied to exchange listing milestones is another lever. If the project achieves a Tier 1 listing within a defined window, a portion of the founder's allocation unlocks early. This aligns the incentives of the team with the liquidity interests of investors while giving the founder a tangible path to financial stability.
Finally, founders should consider establishing a modest salary drawn from the treasury from day one. Treating founder compensation as an afterthought—something to be addressed after the token appreciates—is a pattern that has left talented builders in genuine financial distress while their protocols accumulated nominal value.
The Ecosystem's Uncomfortable Silence
Part of what makes the phantom liquidity problem so persistent is that it is rarely discussed openly. Admitting that a successful raise has not translated into personal financial stability feels like a contradiction—one that founders worry will undermine confidence in their project.
But the silence is costly. Founders who are financially stressed make worse decisions. They accept unfavorable terms from late investors who sense desperation. They cut engineering budgets at precisely the wrong moment. They burn out.
The Web3 ecosystem has built extraordinary mechanisms for creating theoretical value at speed. The next frontier is building the structural literacy to distinguish that theoretical value from the kind of capital that actually keeps a company—and its builders—operational.
Paper wealth is not nothing. But it is not payroll, either.